
بِسْمِ اللّٰهِ الرَّحْمٰنِ الرَّحِيْمِ
A real sale. Not a loan.
Mobilistan offers mobile phones through a Musawamah-based deferred sale structure. The Sharia structure, contractual documentation and transaction process have been independently reviewed and certified by Al Hijrah Sharia Advisory Services.
Sharia Compliance Certificate, AHC/MOB/SCC/2026/006. Issued by: Al Hijrah Sharia Advisory Services. Valid: 16 September 2026 to 16 September 2027.
What is Musawamah?
Musawamah is a form of sale in which the seller and buyer mutually agree on the selling price of an asset. Unlike Murabahah, the seller is not required to disclose its original purchase cost or profit margin to the buyer.
In Mobilistan's model, you select a specific mobile phone. Mobilistan acquires the identified device and then sells it to you at an agreed deferred sale price, payable according to the agreed payment schedule.
The key principle
Mobilistan must own the phone before selling it to the customer.
The transaction is therefore structured as a sale of an asset, rather than a loan of money.
A sale you can understand
- A genuine sale
- You are purchasing an identified mobile phone from Mobilistan. Mobilistan is not lending cash to you.
- Ownership before sale
- Mobilistan acquires the phone before entering into the Musawamah sale with you.
- A fixed agreed price
- The total deferred sale price is agreed when the sale is concluded.
- No increase in the sale price for late payment
- Once the sale has been concluded, the agreed sale price does not increase merely because an instalment is paid late.
- Everything clear up front
- The total sale price, advance payment, number of instalments, instalment amount and payment schedule are disclosed before the sale is accepted.
- Device security is disclosed
- Where an approved device-security mechanism is used, its operation and relevant terms are disclosed to the customer as part of the arrangement.
Musawamah is a sale — not a cash loan
The fundamental difference lies in the nature of the transaction.
| Mobilistan Musawamah / Interest-based lending | Mobilistan Musawamah | Interest-based lending |
|---|---|---|
| Nature of transaction | Nature of transactionSale of an identified mobile phone | Lending of money |
| What the customer receives | What the customer receivesA mobile phone sold by Mobilistan | Money advanced as a loan |
| Basis of return | Basis of returnProfit arising from the sale of an asset | Interest charged on money lent |
| Ownership of asset | Ownership of assetMobilistan acquires the phone before selling it | A loan does not depend on the lender first owning and selling the financed asset |
| Price / obligation | Price / obligationSale price is agreed when the contract is concluded | Repayment obligation arises from the lending arrangement |
| Late payment | Late paymentAgreed sale price is not increased merely because of delay | Governed by the terms of the relevant lending arrangement |
This comparison explains the basic contractual distinction between Mobilistan's approved Musawamah sale structure and interest-based lending.
Independently reviewed. Formally certified.
Mobilistan's Musawamah-based deferred sale model has been reviewed by Al Hijrah Sharia Advisory Services. The review covers the approved Sharia structure, relevant contractual documentation and transaction process.
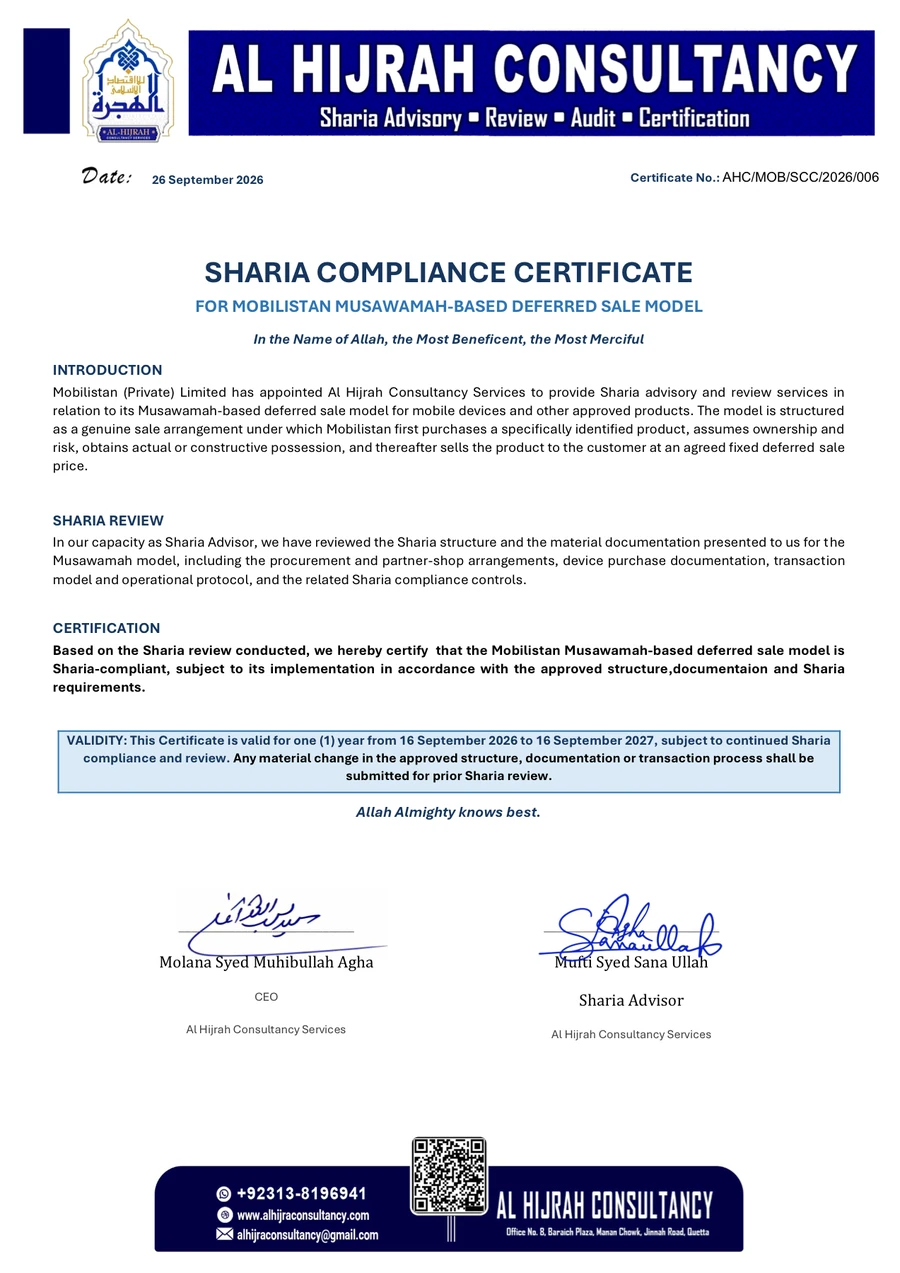
Sharia Compliance Certificate
- Issued by
- Al Hijrah Sharia Advisory Services
- Certificate No.
- AHC/MOB/SCC/2026/006
- Date of issue
- 26 September 2026
- Valid
- 16 September 2026 to 16 September 2027
Independent Sharia review & oversight
Al Hijrah Sharia Advisory Services serves as the independent Sharia advisor for Mobilistan's approved Musawamah-based deferred sale model. Its role includes reviewing the Sharia structure, relevant contractual documentation and approved transaction process to assess their conformity with applicable Sharia requirements.
- Structure review
- Review of the Musawamah structure, sequence of transactions, ownership and possession requirements, and the relationship between the relevant parties.
- Documentation review
- Review of relevant contractual documentation, including the customer sale documentation and relevant partner-shop, agency and device-purchase arrangements.
- Sharia certification
- Issuance of Sharia certification for the approved model, subject to the scope, conditions and validity stated in the certificate.
- Ongoing Sharia review
- Material changes to the approved structure, contractual documentation or transaction process are subject to Sharia review in accordance with the applicable advisory arrangement.
Sharia oversight by Al Hijrah
The approved Mobilistan Musawamah model has been reviewed under the Sharia advisory and review framework of Al Hijrah Sharia Advisory Services.
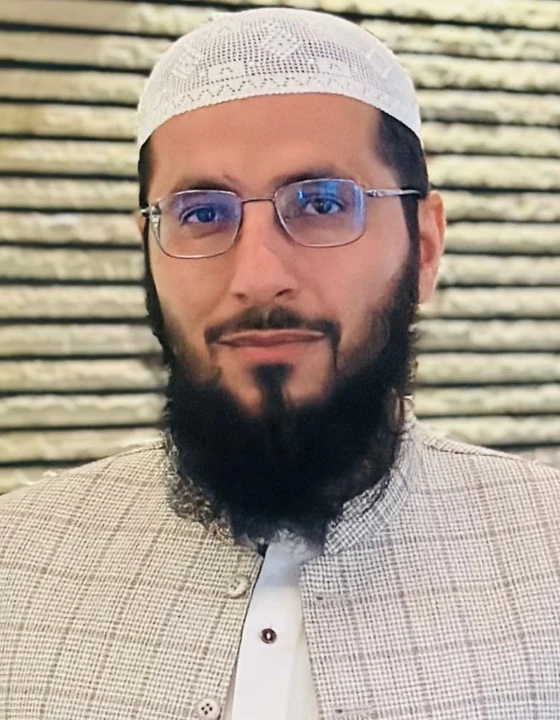
Mufti Syed Sanaullah
Sharia Advisor
Certified Sharia Advisor & Auditor (CSAA – AAOIFI)
Sharia review, advisory and compliance oversight.
A Certified Shariah Advisor and Auditor (CSAA) from AAOIFI, Bahrain, with professional experience in Shariah advisory, Islamic finance, Shariah compliance and audit. He has served on the Fatwa Council of Jamia Darul Uloom Karachi and has extensive experience in reviewing financial transactions, business models, contracts and operational processes from a Shariah perspective. At Al Hijrah he leads Shariah advisory and compliance engagements, and he has delivered training on Islamic finance and Shariah-compliant business practice for financial institutions, organisations and professionals.
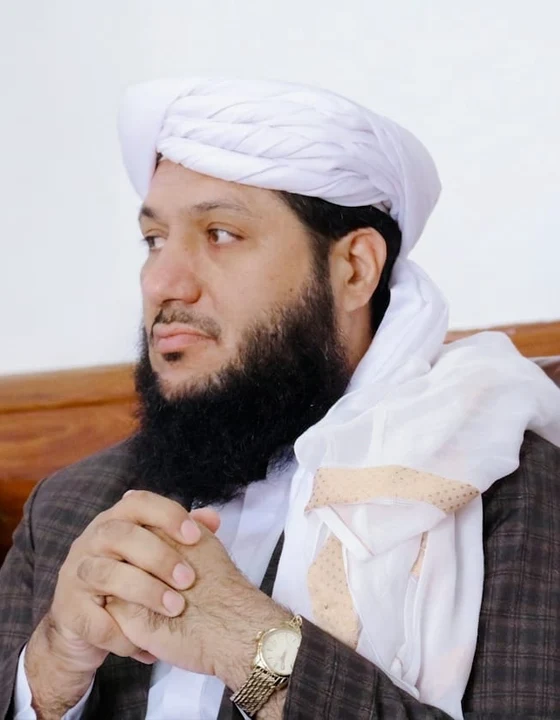
Maulana Syed Muhibullah Agha
Founder & Chief Executive Officer, Al Hijrah Sharia Advisory Services
Institutional oversight and Sharia advisory coordination.
An Islamic scholar, educator and Shariah consultancy professional. He is a graduate of Dars-e-Nizami from Jamia Darul Uloom Karachi and holds an MPhil in Islamic Banking from the University of Balochistan. As Founder and CEO of Al Hijrah he provides strategic leadership in Shariah advisory, Islamic business solutions and institutional consultancy, bringing traditional Islamic scholarship and contemporary Islamic banking together in practical, Shariah-compliant solutions for businesses and institutions.
About Al Hijrah Sharia Advisory Services
Al Hijrah Sharia Advisory Services provides professional Sharia advisory, review, audit and certification services to businesses and institutions.
Its advisory work focuses on reviewing commercial structures, contractual documentation and operational processes from a Sharia compliance perspective and providing recommendations for the implementation of approved structures.
Sharia advisory, review, audit and certification
- +92 313 8196941
- alhijraconsultancy@gmail.com
- alhijraconsultancy.com
- Office No. 8, Baraich Plaza, Manan Chowk, Jinnah Road, Quetta
Common questions
What is Musawamah?
Musawamah is a sale in which the seller and buyer mutually agree on the selling price. The seller is not required to disclose its original purchase cost or profit margin. In Mobilistan's model, the phone is acquired by Mobilistan and then sold to the customer at an agreed deferred price.
Is Mobilistan giving me a loan?
Under the approved Musawamah structure, Mobilistan does not lend you money to purchase the phone. Mobilistan acquires the identified phone and then sells that phone to you at an agreed deferred sale price.
Does Mobilistan own the phone before selling it to me?
Yes. Under the approved transaction structure, Mobilistan must acquire ownership and possession of the identified phone before concluding the sale with the customer. This sequence is an important part of the Sharia structure.
Why can the deferred price be higher than a cash price?
In a Sharia-compliant sale, the parties may agree on a deferred sale price that differs from a cash price, provided that one final sale price is clearly agreed when the sale is concluded. Once the sale is concluded, the agreed sale price becomes the contractual price and is not subsequently increased merely because of delay in payment.
If I pay late, does the sale price increase?
No. The agreed sale price does not increase merely because an instalment is paid late. The customer's other obligations and any approved device-security measures remain subject to the terms of the relevant agreement.
Why can the phone be locked?
Mobilistan may use an approved device-security mechanism in accordance with the customer agreement. Its purpose and operation are disclosed to the customer before the sale is accepted. Its use does not increase the agreed sale price or convert the transaction into an interest-bearing arrangement.
Who reviewed Mobilistan's Sharia compliance?
The approved Musawamah structure, relevant contractual documentation and transaction process have been independently reviewed by Al Hijrah Sharia Advisory Services, which has issued the relevant Sharia Compliance Certificate subject to its stated scope, terms and validity.
Our commitment to Sharia compliance
Mobilistan is required to implement the Musawamah model in accordance with the structure and documentation reviewed and approved by Al Hijrah Sharia Advisory Services.
The Sharia certification applies to the approved structure and process as reviewed. Any material modification to the transaction structure, contractual documentation or operational process should be submitted for Sharia review before implementation.
A transparent sale. A clear price. A Sharia-reviewed structure.
Understand the transaction before you buy.
وَاللّٰهُ أَعْلَمُ
And Allah Almighty knows best.